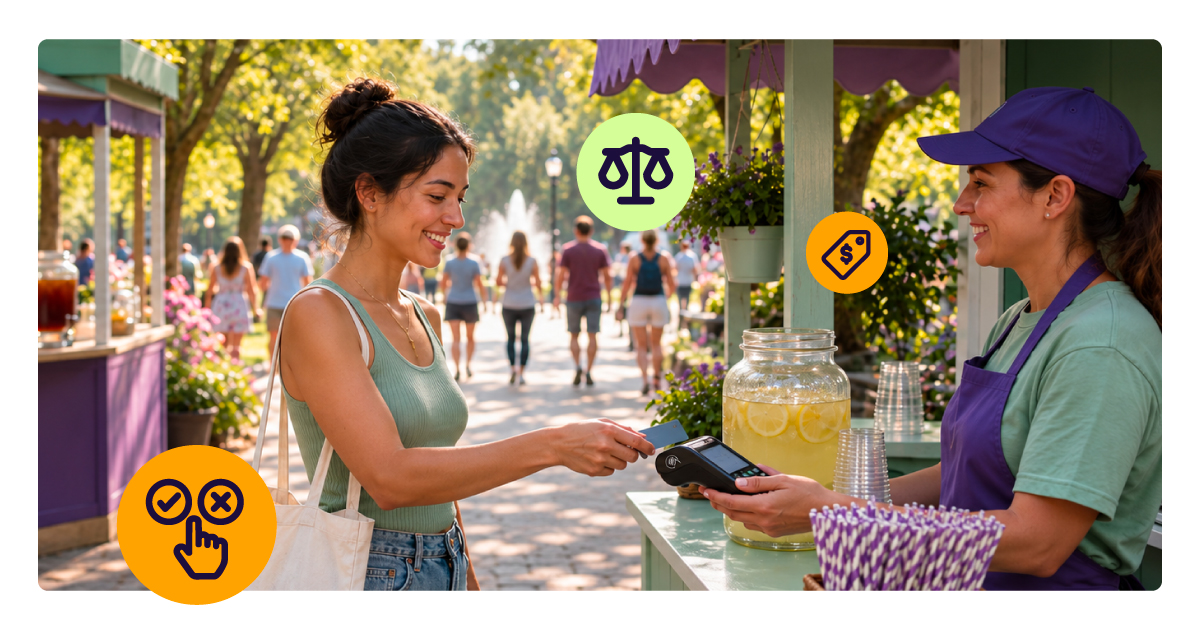
Picture two refreshment stands across from each other in a busy park. One sign reads “Frank’s Flat Rate Refreshments.” The other reads “Izzy’s Interchange Cafe.” Same drinks, same customers, two different ways of arriving at a price.
That’s the simplest way to understand the two most common approaches to payment pricing: Flat Rate and Interchange Plus. If you’re embedding payments into your software, you have to choose one or decide whether offering both makes sense. The right answer depends on who’s buying, not on which model is objectively “better.”
How Flat Rate Pricing Works
Frank sells lemonade and iced tea. Each one costs him a different amount to make, but he prices every drink the same way: one average cost, one standard markup, one simple price. Whether a customer pays with a Visa card, a Mastercard or anything else, the merchant pays one consistent rate.
That’s Flat Rate pricing. The processor blends the underlying costs of different transaction types into a single number, so the merchant never has to think about what kind of card just got swiped. It’s predictable and it’s easy to explain.
How Interchange Plus Pricing Works
Izzy sells the same drinks, but she prices each one based on what it actually costs her to make, then adds the same markup across the board. In payments terms, that markup is a fixed amount on top of interchange, the underlying cost associated with processing a particular card transaction. Interchange rates vary depending on factors such as card type, transaction method and merchant category.
So a debit card swiped in person might cost less than a rewards card entered online, and the merchant sees that difference reflected in their rate. The markup can remain fixed while the underlying cost changes from transaction to transaction.
What Determines Which One Is Right for a Merchant
Back at the park, neither Frank nor Izzy has the “better” pricing model. The better choice depends on who’s standing at the counter. What matters is the merchant’s card mix and volume, alongside factors such as average transaction size, sales channel and how much pricing simplicity the merchant values.
A merchant with lower or less predictable volume may prefer Flat Rate because it provides a simple, consistent way to understand payment costs. This can be particularly attractive to merchants that don’t want to navigate the complexity of different interchange categories or see their effective rate vary with every transaction.
A merchant with higher, steadier volume and a card mix that leans toward lower-cost categories, like debit and in-person transactions, may find Interchange Plus more attractive. Because they’re paying the underlying interchange cost plus an agreed markup, they can benefit when their transaction mix results in lower interchange costs rather than paying a single blended rate.
What It Means for Your Platform’s Revenue
There’s a third stakeholder in this story: the software platform behind the payment. For platforms, choosing a pricing model isn’t only about what the merchant pays. It can also shape how you position payments, how easily you can explain pricing and how you manage your margins.
With Flat Rate, the price the merchant pays typically remains consistent, even though the underlying cost of processing individual transactions can vary. That makes the merchant experience predictable and can simplify pricing conversations, onboarding and support. However, because underlying costs depend on transaction mix, the economics behind that flat rate can vary too.
With Interchange Plus, the platform’s agreed markup can remain consistent while the total price the merchant sees moves with the underlying interchange cost. That transparency tends to appeal to larger, more sophisticated merchants, especially those with a lot of debit or in-person transaction activity, where the savings from lower-cost transactions are real and easy to point to.
In Frank’s world, simplicity makes the pricing conversation easier. In Izzy’s, greater transparency can appeal to customers who want to understand exactly what they’re paying for. Platforms face a similar trade-off.
For software platforms serving a broad base of merchants, Flat Rate can offer a simpler proposition to sell and support. Interchange Plus can become more attractive when serving larger or more payments-savvy merchants who process enough volume to notice the difference and want more visibility into their underlying processing costs.
The commercial implications will depend on your pricing arrangement, merchant mix and payments strategy, so neither model automatically delivers more predictable or higher margins in every scenario.
Choosing the Right Model
The important thing isn’t picking a side. It’s understanding your merchants well enough to match the pricing model to how they actually operate, and understanding your own business well enough to know how pricing supports your growth and monetization strategy.
Some platforms offer both and let merchants self-select based on their volume and card mix. Others standardize on one model to keep onboarding and support simple. Some may even segment pricing based on the types of merchants they serve. Whatever the approach, let the data guide the choice: who your merchants are, how they accept payments, what they value in a pricing model and how payments fit into your broader platform strategy. Don’t base it on which model sounds more sophisticated.
Frank and Izzy can both run successful stands because they’re serving different customer needs. The same is true for software platforms. The goal isn’t to prove that one pricing model wins, but to choose the approach, or combination of approaches, that fits your merchants and your commercial strategy. For software companies embedding payments, having the flexibility to support different pricing approaches can make it easier to serve a wider range of merchants as the platform grows.
NMI helps software platforms embed payments, keep control of their pricing model and earn revenue from payments as they grow. To see how we can support your payments strategy, talk to our team.